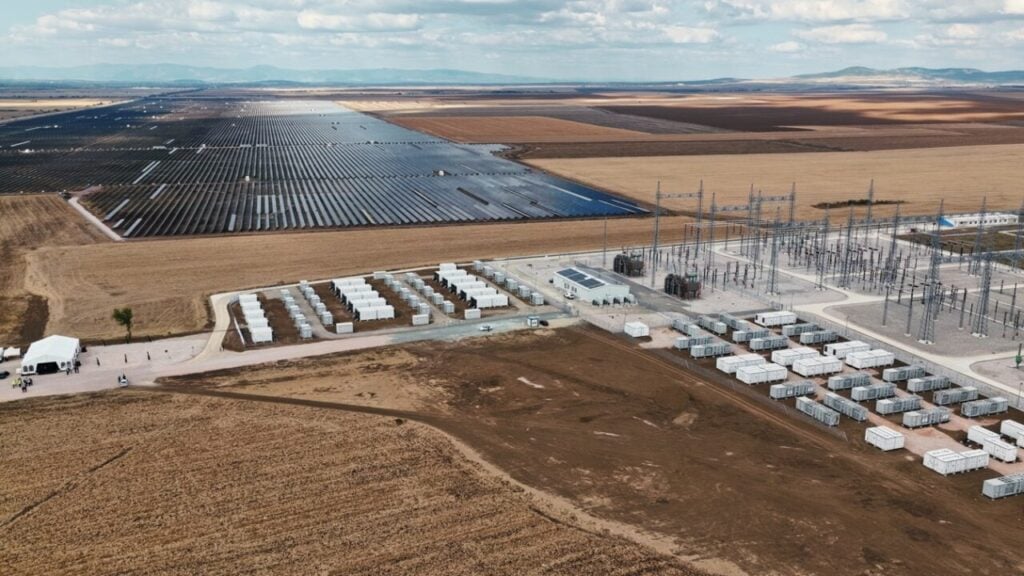
Investing in a portfolio that includes solar PV projects and battery energy storage systems (BESS) is a key tool to reduce exposure to power price-related risk in Europe, according to analysis from Swiss-headquartered pricing platform Pexapark.
The company’s head of quantitative advisory, Karolina Hartzell, and EVP of advisory, Jens Hollstein, led a webinar on that topic this afternoon. Hartzell noted that, historically, solar capture value and BESS price spreads have moved in opposite directions, meaning that one type of asset can become more valuable as the value of the other declines.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
“There is a certain mitigation effect,” explained Hartzell. “We can see that whenever solar [capture value] is dipping, we see an offset effect, so an increase in price spreads [for BESS]. There is a strong relationship between these two variables; it is a negative relationship, so positive deviations in one are offset by negative deviations in the other.”
This dynamic means that opportunities for offtakers in solar PV and BESS assets can improve and worsen in opposition to one another. Hartzell said that lower solar capture rates translate to “opportunities for storage,” and used price data in Spain and Bulgaria to illustrate how the penetration of solar and BESS, respectively, can affect this trend in individual markets.
“Spain is a market with a lot of interest in flexibility, where we see more and more combined deals, but the capacity of BESS compared to whole demand is not very high,” said Hartzell, suggesting that BESS capacity accounts for less than 25% of total electricity demand and that this “very clearly” translated to an erosion of solar value, while “arbitrage opportunities for batteries keeps getting higher”.
“On the other side, if we look at Bulgaria, it’s a market where there’s a lot of BESS—[accounting for] 80% of peak demand capacity—so it’s a market with a lot of flexibility and we can really see in 2026 that [this trend] is starting to reverse; there’s an increase in solar value and that’s followed by a reduction in price spreads.”
However, while the scale and maturity of Bulgaria’s BESS market could make it something of an outlier, Hartzell said that she expects this trend to change in the future, where both solar capture rates and BESS price spreads could decrease in tandem.
“If we look at implied solar capture rate—which we can essentially approximate by looking at the relationships between the solar capture price, solar pay-as-produce and the baseload—we see values of around 46%,” she said, looking forward. “In history, the most recent observations were about 55-56%, so we see a discount in the implied solar capture rate in the future [implying] the solar value is going to go farther down.
Hartzell said that the forecast battery price spreads are “a bit more level around 115%”, compared to “most recent observations” of around 140%.
“There’s a discrepancy that this is nowhere we’ve seen. This is quite interesting to see, because if you look at the relationship, generally as one was going down, the other one was increasing; here, we see lower values for both, when compared to their history.”
Diversified portfolios, not necessarily co-location, have potential
Hartzell added that it is unclear if this will be a long-term trend, or the result of “conservative” pricing in the short-term, an assessment that Hollstein echoed.
“Having seen these market observations, it’s unclear if this is just very conservative pricing or an indication that the market expects a totally new price shape going forward,” he said. One immediate solution could be to invest in solar-plus-storage projects, which often find value as flexible and resilient assets in times of uncertainty, and Pexapark’s own figures show an uptick in power purchase agreements (PPAs) signed for solar-plus-storage projects in Europe.
But Hollstein was clear that investments can be made into separate solar and storage assets, rather than a single co-located project.
“‘Is this another co-location webinar?’” he asked rhetorically at the beginning of the webinar. “No, it should not be another co-location webinar. We really want to look at portfolios where you could potentially combine standalone PV and BESS. It’s how the two pricings align in the market between BESS and PV.”
“If you already have a combined portfolio, first of all, congratulations because you already have a portfolio that has certain resilience!” he continued. “You could go for joint offtake contracts, to avoid the double dip on the hedging side, if you find a good offtaker who understands these dynamics.”
“There is very strong evidence that combined PV and BESS carries less risk and less volatility for the whole portfolio value, so whatever agreement [is signed], this should be taken advantage of,” agreed Hartzell.