The average price of a solar power purchase agreement (PPA) in Europe increased 0.4% between the second and third quarters of 2026, according to the latest financial data from LevelTen Energy.
The analyst attributed this increase to “macroeconomic factors”, including higher solar module prices and highest interest rates, which have pushed up development costs and, by extension, encouraged generators to sign slightly higher-priced offtake deals.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
LevelTen’s latest figures replace the conventional expression of price data in Euros per megawatt-hour, as has been used in earlier LevelTen reports, with a new index to better reflect change in prices. This index begins with a baseline price figure from eight quarters earlier—expressed as ‘1.00’—and expresses individual quarterly price data in relation to that baseline.
For example, the average price of a solar PPA signed in Europe reached 0.86 against the baseline in the third quarter of this year; this means that the price is 86% of the price reported in the third quarter of 2024, which LevelTen’s Plácido Ostos told PV Tech Premium at the time was €63.64/MWh (US$69.32/MWh). Wind, meanwhile, reached an average price of 0.99 of the Q3 2024 baseline, meaning that average wind PPA prices have only decreased marginally over the last two years, whereas solar prices have fallen at a greater rate.
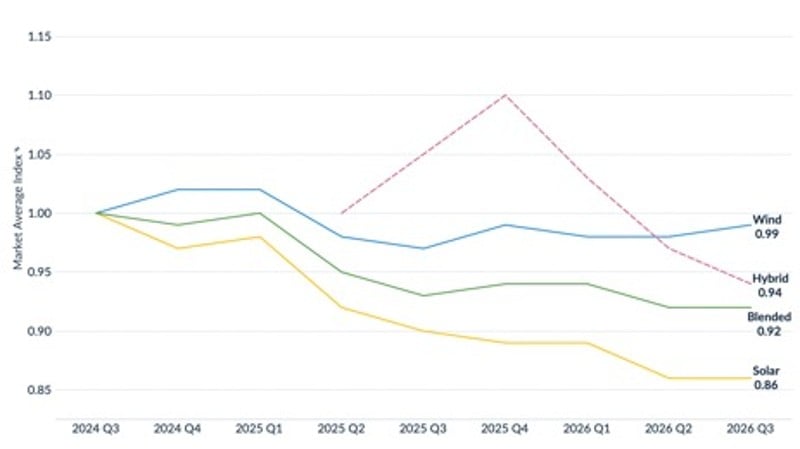
The graph above demonstrates how average PPA prices have changed since the third quarter of 2024, with the slight increase in prices between the second and third quarters of 2026 not offsetting the price decreases seen over a longer period of time. Hybrid PPAs have shown the most dramatic change from one quarter to the next, which could be attributed to the complexity associated with signing deals for renewable energy-plus-storage projects, but also the relative novelty of the hybrid PPA tracker—which covers offtake prices involving projects that co-locate renewable energy generation with a battery energy storage system (BESS)—as a metric.
This was launched for the first time in the last quarter and LevelTen said this quarter that hybrid PPAs have “gained ground” across Europe, with nine markets reporting a hybrid PPA in the third quarter. These kinds of PPAs are particularly popular in regions where there is more curtailment of renewable energy, such as Iberia; LevelTen reports that Spain and Portugal accounted for nearly half of all hybrid PPAs in the third quarter of this year.
LevelTen also said that low PPA prices for standalone solar in Spain means the country has “hit the limits of pricing lower while still retaining financeability.” The analyst reports that the average solar PPA price in Spain was €30.93/MWh in the third quarter, down 1.2% since the second quarter and down 7.7% year-on-year. Hybrid PPAs, meanwhile, saw an average price of €48/MWh, and LevelTen noted that this shift towards hybrid PPAs could also help “move the market forward” and away from these lower prices.
This lends credence to the idea that the co-location of BESS with renewable energy generation, and their inclusion in the same offtake deals, is considered a way to minimise the impacts of curtailment in Europe. In the first half of this year, curtailment reached 2.5TWh in Spain, more than three times the level in the first half of 2025 and 50% higher than the total figure for the entirety of 2024; in response, the government has announced plans to launch a capacity market and US$19.5 billion in new grid infrastructure investments.
However, the same trend was not reported in Germany, which was identified in the second quarter as one of the markets suffering from significant curtailment by LevelTen. In the third quarter of this year, German hybrid PPA prices fell 12.7% from one quarter to the next, a more dramatic change than the 6.8% increase in hybrid PPA prices in Spain over the same period, suggesting that transitioning from standalone renewable energy generation to hybrid projects alone will not eliminate more dramatic swings in average offtake price.
Operational projects account for almost 40% of European PPAs
LevelTen’s latest report also includes operational data for European PPAs for the first time, tracking both offtake agreements for new-build assets and those that have been signed for assets already in operation. The analyst notes that operational project deals make up almost 40% of the deals on its platform, suggesting that buyers are keen to sign offtake agreements for projects where previous PPAs may have come to the end of their duration.
Indeed, LevelTen’s data shows that PPA offers made for operational assets has increased from under 10% of all offers made to the nearly 40% figure reported in the third quarter of the year, showing an increasing demand for these kinds of deals.
“Operational assets naturally lower risk and bring fewer development hurdles and permitting delays compared to new-build projects”, explained Ostos. “For these reasons, they generally represent a faster, and often more cost-effective, route to power compared to new green energy infrastructure. For buyers focused primarily on speed and price over green additionality claims, deals tied to operational projects can be more attractive.”
LevelTen’s European figures, however, do not include a market-averaged PPA price expressed in dollars per megawatt-hour, unlike its report on North America, which includes such a figure.
US solar PPA prices up 4.9 quarter-on-quarter
LevelTen’s North American figures show quarter-on-quarter increases in prices, a trend moving in the opposite direction to Europe. The average price of a solar PPA signed in North America reached US$64.23/MWh, up 4.9% from the previous quarter and the highest quarter-on-quarter growth rate among technologies profiled, which includes wind and blended PPAs but, unlike Europe, does not include hybrid PPA prices.
The North American figures also include a price index expressed around 1.00, as is the case with the European figures, and this demonstrates how solar, despite the recent quarter-on-quarter increase in prices, has experienced a lower price increase over the last two years than other technology types.
Compared to the 1.00 starting point in Q3 2024, the price index of solar reached 1.13 in the third quarter of 2026, meaning that prices today are at 123% of the level that they were two years ago; this compares to an index of 1.27 for wind and 1.20 for blended PPAs.
LevelTen attributes much of the steady increase in solar PPA prices to developers passing on costs, which have been driven up considerably by policy changes such as the introduction of tariffs and minimum import prices under Section 232, to offtakers.
“By combining a 15% blanket tariff with a minimum import price that brings all components to levels comparable to domestically produced counterparts, analysis shows the levies pushing up imported module prices by more than 40%,” reads the LevelTen analysis.