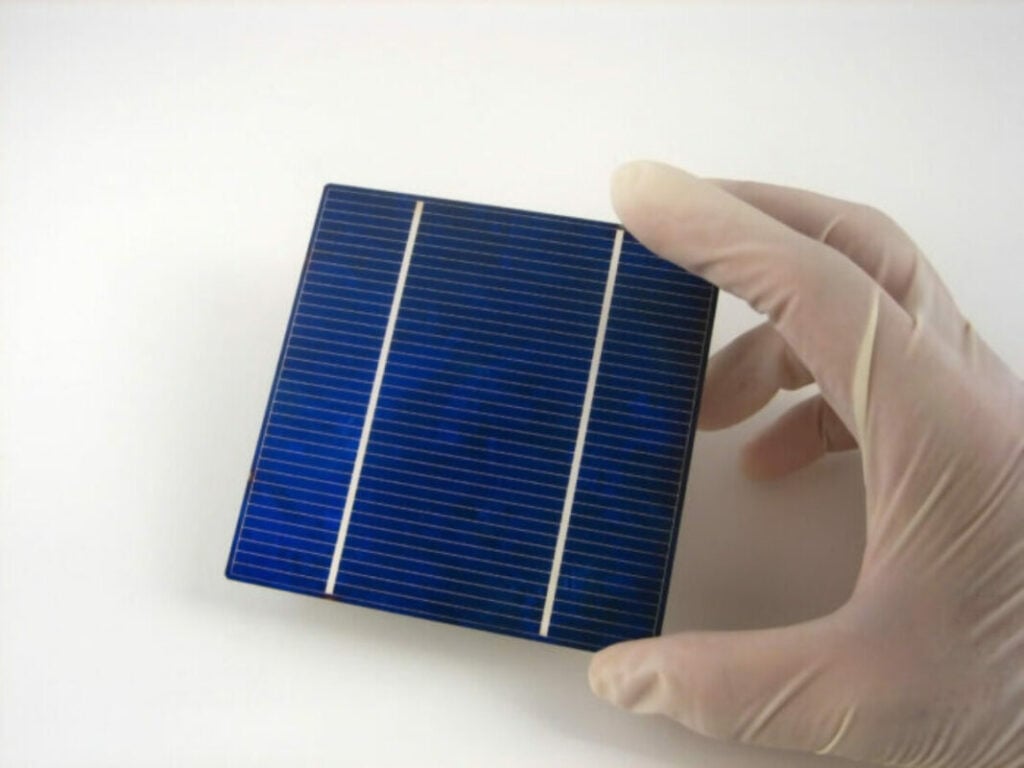
The development of next-generation perovskite solar technology offers Indian PV manufacturers a viable route to owning their intellectual property rather than licensing or importing it because the global science still remains in development.
This was one of the main conclusions from a report published earlier this month by the Indian Solar Manufacturers Association (ISMA), called ‘Perovskite solar – India’s Atmanirbharta opportunity in next generation PV’, which highlighted future opportunities for India’s fast-growing PV manufacturing industry.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
The report highlighted the extent to which polysilicon, wafers and most process equipment used by Indian PV manufacturers are remain “overwhelmingly imported”. “Perovskite is the first solar technology where India can plausibly own the IP rather than license or import it, because the global science base is still being written rather than settled,” the report said.
The trade body highlighted that a provisional category for next-generation cell technologies under India’s Approved List of Models and Manufacturers (ALMM), India’s flagship policy for promoting domestic manufacturing, would give Indian perovskite manufacturers a visible pathway to hone the technology.
This would be structured in two tiers, one for single-junction perovskite and one for tandem architectures. According to the report, this would mirror what the Ministry of New and Renewable Energy (MNRE) has been doing so far by extending its list from modules to cells and soon to wafers.
Moreover, perovskite technology could be the entry point for the Indian solar manufacturing industry to finally own the intellectual property rather than license or import it, the report said. Even though the Indian solar manufacturing industry has scaled up its domestic capacity over the past five years, from modules to ingots and wafers, this has been achieved through technology licensing, while polysilicon, wafers and most process equipment remain largely imported.
The report notes that India’s current dependence on imported polysilicon and wafers could be eliminated with perovskites. As a first step, it says India could focus on developing domestic capabilities with single-junction perovskites before moving to silicon-perovskite tandem technology, thereby building on its existing and growing TOPCon cell production base under India’s Performance-Linked Incentive (PLI) scheme.
The reasoning for starting with single-junction perovskites is that it eliminates the need to match a perovskite top cell to a textured silicon bottom cell, which is currently an engineering challenge and limits tandem module yields globally.
“For an industry with limited process depth, starting with a single junction lets Indian manufacturers build absorber, encapsulation and reliability know-how without simultaneously having to master silicon-perovskite interface integration,” said ISMA.
ISMA forecasts 205GW solar cells, 355GW modules annual nameplate by 2030
On top of releasing a report on perovskite, ISMA also published last week a report on India’s solar manufacturing vision through to 2047.
Some of the key data from the report shows that the country currently has an annual nameplate capacity of more than 233GW for modules, above 50GW of solar cells and the first ingot and wafer plant is already up and running, ahead of the planned 2028 introduction of the ALMM list for wafers. The current total invested in Indian solar manufacturing under its PLI scheme has reached US$8.4 billion, with each dollar of incentive from the PLI drawing four dollars of private investment. By 2047, the report anticipates total investment in PV manufacturing will reach US$89 billion, with 70% of all investment from now until then going into polysilicon, wafer and cell production.
By the end of the decade, ISMA forecasts that the Indian solar manufacturing industry would reach an annual nameplate capacity of 20GW for polysilicon, 56GW for ingots and wafers, 205GW for solar cells and 355GW for modules.
The entire supply chain, from polysilicon to modules, would run at 260-372GW per year by 2047.