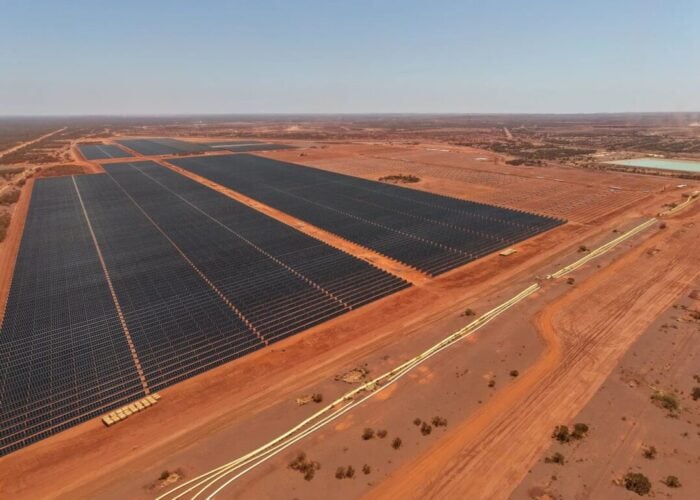
At the end of 2013, based on annual market demand, the top 10 states for solar PV in the US had an aggregate project pipeline of approximately 2,000 non-residential projects. This represents almost 40GW of potential PV capacity.
Project pipelines provide significant insight into individual projects, but also help understand market structures, business models, and future demand levels.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
Figure 1, to the below, shows the total project pipeline levels (all projects yet to be completed), for the top 10 US states, based on total pipeline capacity.
California dominates the 40GW pipeline, with over 60% of capacity, firmly cementing its place as the leading US market. In fact, if California alone was compared on a global level, it would have ranked as the fourth largest global PV market in 2013.
By examining where states are ranked – in terms of pipeline capacity – long-term demand trends can be established. States with smaller pipeline levels may be in danger of declining year on year, as project development activity slows down and current pipeline activity gets depleted.
Conversely, states that rank higher, in terms of project pipelines, may see strong demand growth in the coming years as projects start to be completed.
However, it is worth pointing out that the pipeline relates only to non-residential (commercial/utility) solar PV installations. Therefore, states that have strong residential segments, such as Hawaii, may have smaller non-residential pipeline capacity but retain strong PV ranking status by virtue of residential activity.
Regardless of where individual states rank, in terms of market or pipeline size, the US market offers tremendous long-term growth opportunities. Any PV company (manufacturer, installer or developer) that wants to participate on a global level clearly needs to have a strategy for the US market; within this, it is essential to understand the size of state markets today and also the strength of the project pipelines driving PV demand going forward.
Co-authored with Christine Beadle, downstream market analyst for NPD Solarbuzz