Various disparate pieces of information could indicate that PV module manufacturers could be entering a period of improving margins on their modules, heralding a period of improved profitability not seen for the last three years.
Recently, GTM Research announced that due to growing global end market demand a shortage in PV modules could materialise by the end of 2015.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
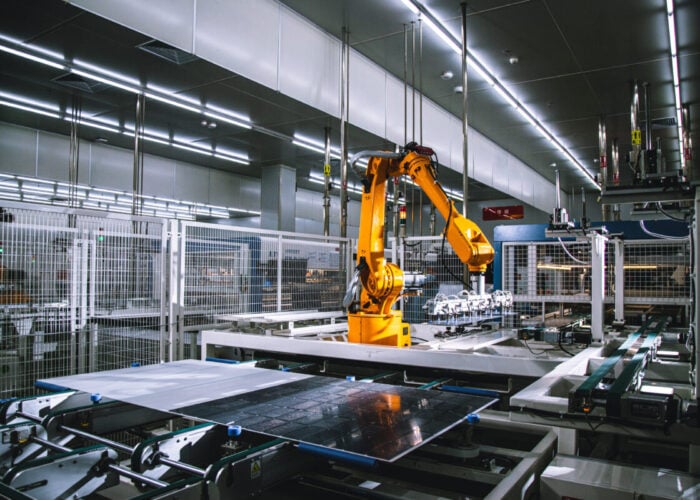
The backdrop was the under-investment by tier-one producers in new manufacturing capacity over the last three years and the fact that many producers were capacity constrained and running plants at near 100% utilisation rates. This occurred due to chronic overcapacity in 2012 and, as a consequence, a significant plunge in module average selling prices (ASP).
Manufacturing cost reductions in this period of profitless prosperity could not keep pace with ASP declines, resulting in the vast majority of manufacturers losing money and worse – bankruptcies, consolidation and so-called zombie companies.
A good example has been Yingli Green, the erstwhile leading PV manufacturer, which has yet to return to profitability on an annual basis.
GTM Research is projecting PV market growth of around 36% in 2015 (55GW), yet manufacturing capacity expansions are only expected to be in 16% range. The market research firm believes that this disconnect is a legacy of the period of profitless prosperity, underlining the cautious approach manufacturers are taking with capital expenditures.
Although a number of tier-one producers returned to profitability in 2014, actual profits remained slim in comparison to pre-2012 and therefore many expansions already announced are being funded from balance sheets and not profits.
PV Tech’s own analysis of capacity expansions and utilisation rates of tier-one producers correlates with GTM’s recent assessment. Shipment figures for the first quarter of 2015, coupled to shipment guidance figures for the second quarter, clearly indicate many tier-one producers are running at near or full capacity.
Capacity expansions already announced, especially for solar cell production, are not expected to come on stream until the fourth quarter of 2015 and beyond.
As far as GTM is concerned the situation could result in module shortages in 2016 and beyond.
Of course, even if shortages as such do not materialise, persistently tight supply would result in module ASP decline stagnating or even increasing.
It should be noted that module ASP decline in 2014 was only around 10% and manufacturing cost reductions were at a similar rate.
Coupled to further manufacturing cost reductions of a similar pace expected in 2015, margins for many tier-one producers should actually improve and overall profitability follow suit.
Polysilicon prices on their way down
However, if we look further upstream to polysilicon capacity expansions and actual ASP declines of this key cost material, PV manufacturers are likely to get a secondary boost to margins.
Depending on which data you look at, polysilicon production is increasing, with much of the new capacity coming on stream in the second half of 2015.
Polysilicon prices decreased last year as supply continued to outpace demand, yet ASP declines were fairly muted and fell below US$20/kg.
Current forecasts expect further declines of around 20% year-on-year with prices averaging around US$17/kg by year-end.
Further polysilicon capacity expansions are expected in 2016 and these are primarily expansions with next-generation, lower-cost technology such as Fluidised Bed Reactor (FBR), setting the scene for more ASP declines, despite continued end-market demand growth for PV.
Therefore several stars are expected to align that provide PV manufacturers with opportunities to improve margins in the second half of 2015 and significantly in 2016.
Should the alignment take place, further and more meaningful capacity expansions could result.