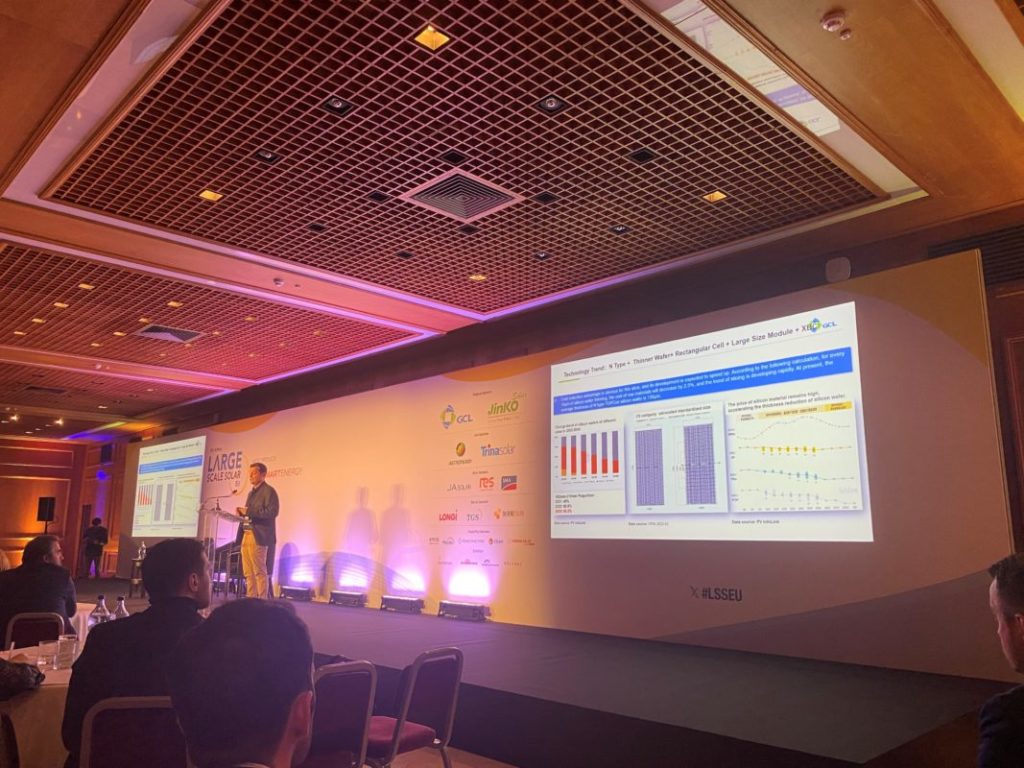
Tunnel oxide passivated contact (TOPCon) solar cell and module technology will dominate the mainstream of the solar PV market in 2024-25, coming to ultimately replace the long-standing reliance on passivated emitter rear contact (PERC) technology, according to Vitor Rodrigues, technical director, Iberia & LATAM, at solar manufacturer GCL system integration.
Speaking at the Large Scale Solar Europe summit today, the headline of his presentation was that 2024 would see the “very fast” phasing out of PERC, that it “will be a hard year for PERC, and PERC will start to disappear.” He also confirmed that GCL no longer produces p-type PERC cells.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
Indeed, concurrently with GCL’s presentation at the summit today, fellow major solar manufacturer JinkoSolar was conducting a talk on its “n-type technology leadership”. For around half an hour, the entirety of the formal discussion at the summit was looking ahead to the n-type transition in module technology.
TOPCon over HJT
Rodrigues discussed the industry shift from p-type PERC to n-type TOPCon, and the market conditions that have contributed to its rise over heterojunction technology (HJT) products.
Chiefly, he said, the shift to TOPCon was made possible by the relative ease that manufacturers have in shifting their production lines from PERC. TOPCon production lines are seemingly a logical successor to PERC: “When we changed from p-type to n-type, the impact on the manufacturing process was not big. When we changed from PERC to TOPCon, there was an impact but it was also not big.”
He said that the main change came from the amount of silver that the production used, as TOPCon makes more concentrated use of rare metals. “[The change] was not really in regards to the machinery or the manufacturing process.”
By contrast, an HJT production line differs significantly from the PERC/TOPCon process. Rodrigues said that with HJT “the cell is not the same concept – we don’t speak about ingots and wafers [with HJT], we speak about ‘the sandwich’; where the nanocrystalline and thin film parts will combine with the crystalline silicon.” This, in short, means that the investment to upgrade a factory for producing HJT is far higher than TOPCon.
However, the real clincher for TOPCon as the heir apparent to PERC was module price. Over the last year, the average price of modules has plummeted, making an already small-margin business even more dependent on scale to stay afloat. This made the extra expenditure for an HJT production line – which Rodrigues said was envisioned for 2024 by a number of manufacturers a couple of years ago – an unjustifiable commitment.
Now, in a year which is already predicted to be difficult for major silicon-based solar manufacturers (almost all of which are switching or have switched to TOPCon), Rodrigues said that the technology’s mainstream dominance is set to continue through 2024 and 2025.
Beyond this, he predicted that HJT would have its day in the sun in 2025/26, alongside tandem perovskite products that are maturing in laboratories and back contact (BC) technology.
BC modules have great potential in terms of cost, conversion efficiency and degradation levels (all of which were the drivers behind the adoption of TOPCon over the last year), but they lack the bifaciality of other technologies. Whilst BC modules can produce electricity from their undersides, the nature of their construction (the contacts are on the back) means that the rates are far lower than other options. As such, Rodrigues predicted that the technology will become dominant in specifically monofacial uses, like floating solar, rooftop PV and building-integrated PV.