Recent analysis has underscored the world-beating economics of solar coupled with single-axis trackers. But for developers, choosing the optimal mounting is a highly project-specific calculation that may result in alternative configurations.
In the second part of this series, Henner Jahnke of Jurchen Technology explores whether dramatically lower module prices relative to structural and installation costs warrant a fresh look at high-density east-west fixed systems over tracking alternatives.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
Why high-density east-west systems deserve a fresh evaluation?
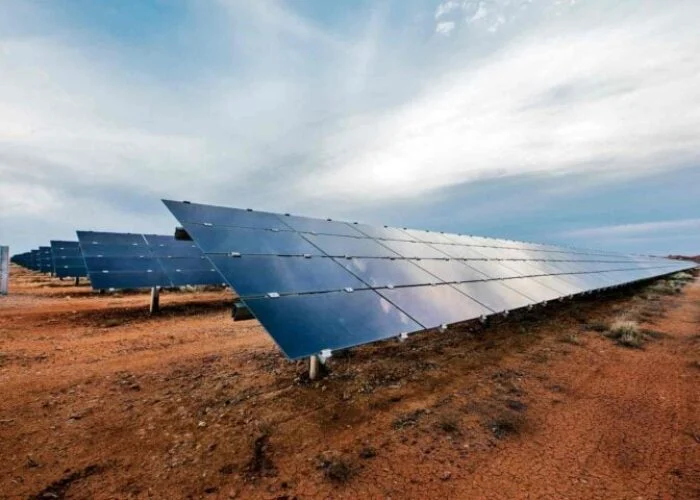
Wood Mackenzie’s widely cited LCOE analysis concludes that single-axis trackers (SAT) represent the most economical design for many large-scale photovoltaic projects.
This assessment is largely based on the higher specific energy yield achieved through solar tracking. However, in light of today’s cost structures, market dynamics and system constraints, a more differentiated evaluation appears warranted.
From module yield to system economics
For many years, the economic logic was straightforward: modules represented the dominant share of total system cost. It therefore made financial sense to extract the maximum possible kilowatt-hours from every installed module.
The 15-25% energy gain typically attributed to trackers justified additional steel, mechanical components, larger row spacing and more complex installation.
Today, the situation has changed significantly. PV modules are available at historically low prices, while steel, civil works, logistics, labour and financing costs have gained relative weight. As a result, the key optimisation metric is shifting away from “yield per module” toward overall system economics — that is, total investment efficiency, land-use efficiency, risk profile and the practically usable energy output per installed megawatt.
Land-use efficiency as a strategic variable
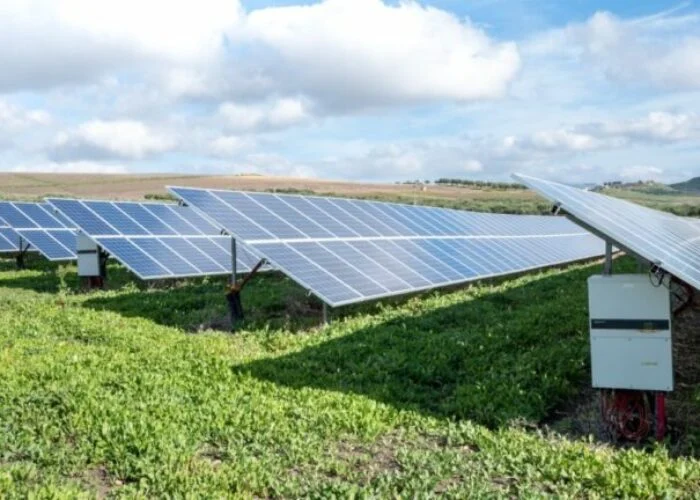
Fixed east-west systems with low tilt angles achieve a lower specific yield per module than trackers. Yet this difference can often be economically offset by a moderate increase in DC capacity. Given today’s module prices, oversizing on the DC side is no longer structurally prohibitive.
More importantly, low-tilt east-west layouts enable very high installation density. Minimal row-to-row shading allows significantly more capacity per hectare. Lightweight high-density systems such as PEG illustrate this potential, with achievable installation densities of approximately 2.1MW per hectare.
In markets where land availability and lease costs are increasingly critical, optimising yield per hectare becomes as relevant as optimising yield per module.
DC-AC ratio and clipping: an overlooked lever
Another economic advantage lies in DC-AC overbuilding. East-west systems typically produce flatter generation curves with reduced midday peaks. This allows for higher DC-AC ratios without causing significant clipping losses, thereby improving inverter utilisation over the course of the day.
In strongly peak-oriented systems, pronounced midday production can more quickly lead to clipping or grid export limitations. Additional DC capacity in such cases does not translate into proportionally higher usable energy. Where grid connection capacity is fixed or constrained, maximising the usable annual yield relative to AC infrastructure becomes more relevant than maximising instantaneous peak output.
In this context, east-west systems can enable a more balanced use of installed infrastructure and reduce the risk of underutilised DC capacity.
Material intensity, construction time and installation simplicity
A fundamental distinction between tracker-based and fixed systems lies in structural complexity. Trackers require moving components, drive mechanisms, bearings and control systems.
Fixed east-west installations eliminate these elements, reducing mechanical complexity and potential failure points.
Modern lightweight concepts demonstrate that material usage can be significantly reduced. Systems such as PEG require approximately 70% less steel than conventional structures, according to manufacturer data. Installation effort is reported at roughly 400-500 man-hours per megawatt peak for full assembly.
The ability to install without heavy machinery and with standard tools reduces logistics requirements and accelerates construction. In today’s market environment, skilled labour availability is a critical bottleneck.
Highly specialised installation crews are increasingly scarce. Standardised, mechanically simple systems allow substantial portions of the installation to be performed by semi-skilled teams without compromising quality. This enhances scalability, improves scheduling reliability and reduces execution risk.
Shorter construction timelines also directly affect project economics by accelerating grid connection, reducing capital tie-up and lowering interest exposure during the build phase. These factors are often underrepresented in yield-focused comparisons.
Lifecycle considerations and system risk
Tracking systems inherently increase technical complexity through moving parts and electronic control units. While modern trackers are mature technologies, mechanical systems inevitably introduce additional maintenance considerations, spare-part dependencies and long-term operational variables.
Furthermore, modules in tracking systems remain oriented toward optimal irradiation for longer periods, operating more frequently at high output levels and elevated temperatures. Even marginal differences in annual degradation rates can become economically relevant over project lifetimes of 25 years or more.
Fixed systems operate statically, without dynamic mechanical loads or tracking movement. This structural simplicity can contribute to long-term operational stability and reduced systemic risk.
Quantifying the economic shift
The shift in economic logic is measurable.
Modules today account for a significantly smaller share of total project capex than in previous years, while steel structures, civil works and construction costs have gained relative importance.
If tracker systems deliver 15-20% higher specific module yield, high-density fixed east-west systems may simultaneously reduce substructure costs by well over 20%, while also shortening construction schedules.
In addition, increasing DC capacity by 10-20% in a flatter production profile can often be achieved without substantial clipping losses. In such cases, economic compensation is achieved not through additional mechanical complexity, but through comparatively inexpensive module capacity.
Over 20-30-year project horizons, modest differences in material intensity, construction duration and capital binding can influence levelised cost of electricity more significantly than a few percentage points of additional module yield.
Reassessment rather than rejection
Trackers remain a valid option under certain site conditions and irradiation profiles. However, their economic superiority should not be assumed as a general rule, but must always be assessed in the specific project context.
The decisive question is not simply whether trackers deliver a higher yield per module — in many cases they do — but whether this additional yield translates into a lower LCOE under the respective local conditions.
Trackers are particularly compelling where the additional specific module yield is difficult to compensate for economically by adding further DC capacity.
This may be the case where modules represent a very high share of total project costs, or where latitude and irradiation profiles create a particularly large yield gap between tracking systems and high-density fixed-tilt east–west solutions. Under such conditions, it may be more economical to optimise the output of each individual module through tracking rather than compensating for lower specific yield with additional low-cost module capacity.
In many markets, however, the economic equation can look different.
Projects are often shaped not only by yield per module, but also by land availability, grid connection capacity, construction and labour costs, permitting pressure, construction timelines and long-term operational risks.
Under these conditions, a high-density east–west configuration can become economically attractive because, despite its lower specific module yield, it can partially offset this disadvantage through higher installed DC capacity per hectare, reduced mechanical complexity, simpler installation and a more favourable overall cost structure.
Therefore, system selection should not be based on the general assumption that one technology is inherently superior. A project-specific LCOE assessment is more appropriate, taking into account local irradiation conditions, land constraints,
DC-AC design, construction costs, installation effort, grid connection conditions and long-term O&M risks.
Put simply, trackers are particularly attractive where modules are expensive or where the site conditions make the additional yield per module truly necessary. In many markets, however, the equation is often more complex: land use, construction costs, grid constraints and execution speed can be more decisive than maximising the yield of each individual module.
In the first part of this series, GameChange’s CEO Phillip Vyhanek explores the key factors shaping the fixed-tilt versus tracker debate across global markets.