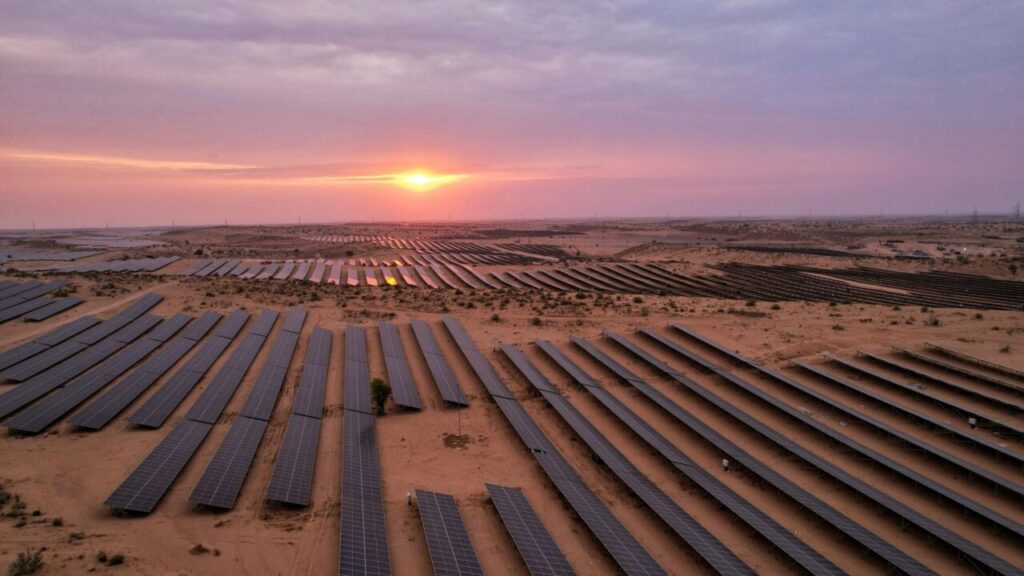
India’s rapid solar deployment has consistently outpaced the industry’s own expectations, but the country’s next phase of growth depends on understanding gaps across the wider manufacturing ecosystem, not just headline capacity additions.
This is according to Rajneesh Khattar, senior group director at Informa Markets India, speaking to PV Tech ahead of this year’s Renewable Energy India Expo and The Battery Show India, which is co-located with the Energy Storage Summit India (ESS India), in Greater Noida on 22-24 October 2026.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
Asked what conversations he is hearing from developers and manufacturers about India’s solar trajectory, Khattar points to a pattern of records being set and then broken.
“India’s renewable energy journey offers compelling evidence of what lies ahead,” he says.
“Year after year, the nation has shattered its own records for installation capacity and demand fulfilment. What was once considered ambitious has become routine; what seemed impossible has become achievable.”
He says that same momentum is now extending into manufacturing.
“Manufacturing ecosystems are rapidly expanding, with domestic and international players establishing production facilities across the country,” Khattar says.
“Policy frameworks continue to evolve, creating incentives for both local manufacturing and large-scale deployment. Public-private partnerships are accelerating technology transfer and localisation, ensuring that India doesn’t merely import solutions but develops indigenous capabilities that can serve both domestic needs and export markets.”
Khattar frames Renewable Energy India Expo as a venue built around that shift.
“Flagship events like our Renewable Energy India Expo & The Battery Show India, scheduled from 22-24 October 2026, have emerged as critical catalysts where the future of India’s energy landscape takes shape,” he says.
“Here, developers and utilities engage directly with global technology providers, exploring the latest innovations in battery chemistry, grid integration systems, and advanced energy management platforms.”
Renewable Energy India Expo & The Battery Show India is co-located with the Energy Storage Summit India, now in its second annual edition, and offers a dedicated agenda for asset owners, developers and policymakers working through the commercial and regulatory questions shaping India’s storage build-out over the coming year.
Cell manufacturing investment is scaling, but supply chain complexity extends well beyond the headline value chain
That manufacturing momentum is already visible in project announcements.
Indian PV module manufacturer Solarworld Energy recently formed a joint venture with Rays Power Infra to develop a 2.4GW solar cell manufacturing facility in Madhya Pradesh, targeting commercial production by June 2027 at a 41.3-acre site in Narmadapuram district, part of a broader wave of cell manufacturing investment moving through India’s pipeline as the country builds out its solar supply chain beyond module assembly.
But scaling that manufacturing base involves more than the five or six products most industry conversations tend to focus on, according to Ankit Singhal, CEO of MAPPES.io, a digital platform that maps industrial supply chains.
Singhal, whose platform tracks the solar value chain from polysilicon through to end applications, has warned that overlooking adjacent products, such as the isostatic graphite parts, quartz crucibles and argon gas needed for crystal growth furnaces, creates bottlenecks that emerge once manufacturing plants are established.
“These are the products that will need to be localised very soon, because again, you can’t rely or depend on some other country,” Singhal said, pointing to China’s dominance of ingot pullers and graphite components specifically.
Singhal noted that India’s own manufacturing build-out has already moved through panels, then cells, then wafers and ingots, a sequence he says is now beginning to repeat in other developing solar manufacturing markets.
Procurement mechanisms and digital infrastructure are shaping how quickly deployment can scale
That manufacturing conversation is unfolding alongside procurement mechanisms designed to guarantee near-term demand for Indian solar developers.
The Ministry of New and Renewable Energy’s (MNRE’s) Solar Energy Corporation of India (SECI) recently tendered 700MW of interstate transmission system-connected solar capacity for commercial and industrial offtake in Odisha, structured under a build-own-operate model with 25-year power purchase agreements, and designed so participating projects qualify for an exemption from India’s domestic manufacturer-favouring hardware rules.
That structure illustrates the kind of policy scaffolding Khattar says continues to evolve around both deployment and manufacturing incentives.
Coordinating India’s growing base of solar generation, alongside a rapidly expanding population of distributed and rooftop assets, also depends on digital infrastructure more than it does on physical hardware.
India’s Ministry of Power has been developing the India Energy Stack, a digital public infrastructure initiative intended to provide standardised digital identities and data exchange for grid assets as the country’s electricity system becomes increasingly decentralised.
The initiative follows a first phase of India’s renewable energy transition defined largely by capacity additions, with the country adding approximately 45GW of installed solar capacity in the last financial year alone, and rooftop solar capacity rising more than 47% over the same period.
A 12-month proof of concept for the India Energy Stack is currently underway across distribution utilities in Delhi, Gujarat, Andhra Pradesh, Uttar Pradesh and Mumbai, testing the interoperability and data governance needed to manage that scale of distributed generation.