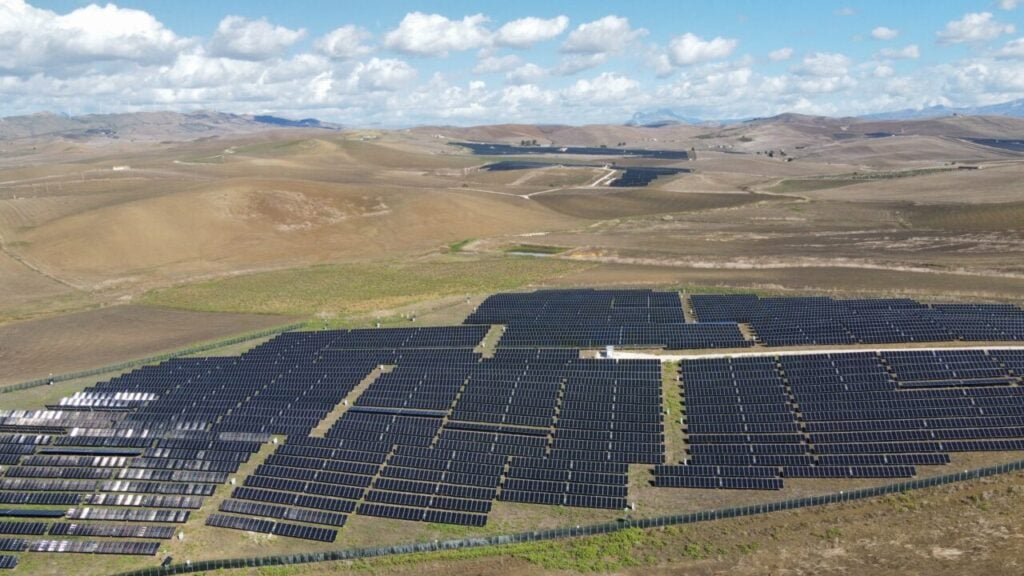
Earlier this month, at the SolarPLUS Europe 2026 conference in Milan, the shifting dynamics affecting the continent’s solar developers were laid bare. Grid constraints, negative prices and the massive expansion of utility-scale solar capacity across Europe between 2022 and 2025 have made standalone solar development less simple. Governments have also started requiring more integrated technology offerings, and overall growth projections have somewhat stalled.
This is manifesting in more developers transitioning to become independent power producers (IPP). One speaker on the opening morning of the conference said this represented a “quantum leap”, requiring moving from simply developing projects to owning, operating and managing the energy production of those sites. Things are further complicated by the growing imperative to bring energy storage into the equation.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
PV Tech Premium sat down with Cristiano Spillati, managing director of Italian renewables developer Limes Renewable Energy, on the sidelines of the conference to discuss the dynamics of that transition, the way that Italy’s solar market compares with the rest of Europe and which sorts of companies will be best placed to succeed.
Italy – Europe’s ‘most exciting’ prospect
Italy has been singled out by some as the “most exciting” European market for solar development. Where standalone PV development is losing viability and becoming complicated in other major EU countries, Italy has been a haven for pure PV generation without the same imperative for energy storage capacity seen in markets like Spain and Germany.
“We need to incentivise pure solar generation [in Italy] because we are behind with our targets for 2030,” Spillati says. “There is 8GW that has been awarded in tenders recently which needs to be built.” He expects the total amount of standalone tendered capacity to reach 12GW by 2028, which will require substantial EPC and logistical capacity to build.
But after that, with the planned introduction of the FER-Z tender in 2028, developers in Italy will have to submit a proposal for a flexible and consistent power generation profile to be awarded a contract. This is a far more complex proposition than just building a project to receive an offtake agreement, even with the recent FER-X auction that imposed the EU’s alternative supplier procurement criteria.
“You will need to be able to provide a combined offer,” Spillati explains. “You need to be able to combine your solar plus BESS, maybe if you have some wind… but solar standalone wouldn’t work.”
This is closer to the sort of offering currently being sought in other major markets – last month, Jan-Philip Kock, chief of staff at German IPP Encavis, told us that in many European markets, “Just having the abilities to develop and build a solar plant is not really something people pay for anymore.” The changes coming down the track in Italy are already underway in other countries, though few auction structures have garnered the attention or praise of the Italian.
Spillati’s company, Limes, is currently fundraising for its transition from a developer to an IPP. “At the moment we have 50MW in the FER-X NZIA [auction]; this will be the first one that we build. And then we have approximately another 120MW that is approaching ready to build, and this will participate in the next two to three rounds. And after that, I hope we will be ready in terms of structure, both financially and organisational, to participate in this competitive environment.”
The ‘quantum leap’
Pulling off this shift from developer to IPP is “totally” a “quantum leap”, Spillati says.
“As a developer you are used to a feed-in-tariff environment, and with that you have a bracket of how your project could be valued; there’s always a minimum where you can make your margin,” he explains. That no longer applies in much of Europe.
As governments have moved away from straightforward solar generation incentives, developers need to do more. “You could develop, but if you don’t have a clear offtake strategy so that it makes sense to develop in that part of the country, then you run the risk of having a project ready to build, and maybe you can recoup your investment, but that’s it,” Spillati says. “It’s totally different.”
Returning to Kock’s comments last month, people won’t pay for just developing a project.
And it’s not just the developer-to-IPP transition that has changed, Spillati explains. Companies that have recently become IPPs, with a business model of developing and selling a project but retaining a minority stake in it, have to do more to manage new assets as the guaranteed baseline of feed-in-tariffs has disappeared.
“So, you know, it’s not only for pure developers; in general, the environment has become much more complex,” says Spillati.
Fewer developers, more local experts
One almost inevitable result of these broad market changes – an emphasis on flexible generation and storage, the move to market models over incentives, and the increased complexity of the industry – will be consolidation.
“Definitely, that will happen across Europe,” Spillati says. “There will be fewer developers and fewer IPPs” as some pure play developers fall by the wayside. What will emerge will be fewer, more “sophisticated” developers at the top of the industry.
At the other end, though, there will still be demand for smaller developers with local knowledge. “One thing that we need to remember is that renewables is a very local business,” Spillati posits. “People who are still able to originate the opportunity at the local level and be able to take it to the last mile, I think these organisations will still have a role. Especially in a country like Italy, where you don’t have a lot of available land.”
Big IPPs and utilities that will take a greater share of project ownership “rely on a network of external developers” to get projects built and approved, Spillati continues. “They need local people to go to the local authorities. They cannot do it. You need to really understand the local environment to be successful.”
Those who suffer as the European solar market changes will likely be middle-sized developers unable to adapt to more complex and difficult market demands and without deep local roots and expertise.