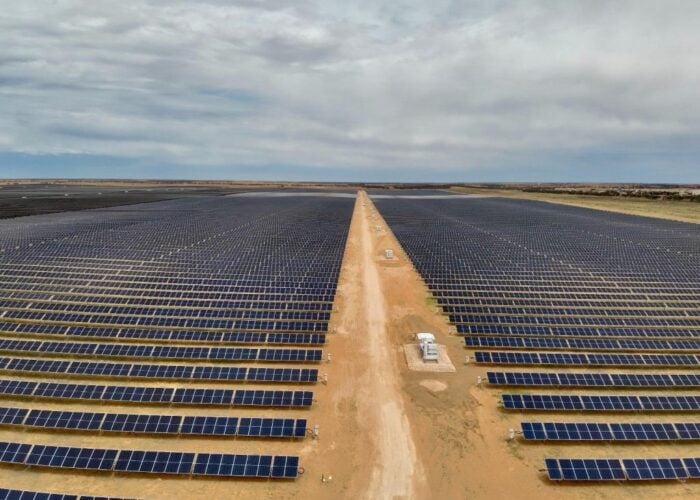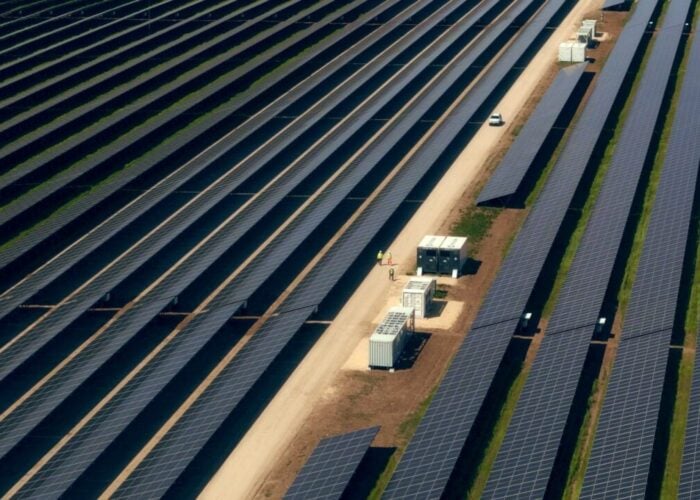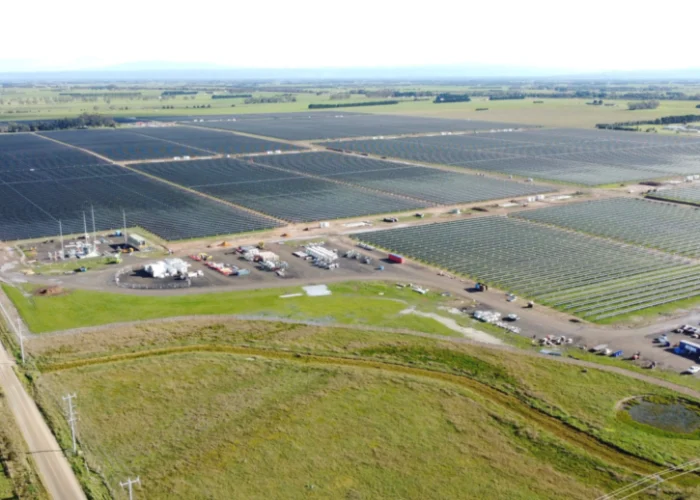
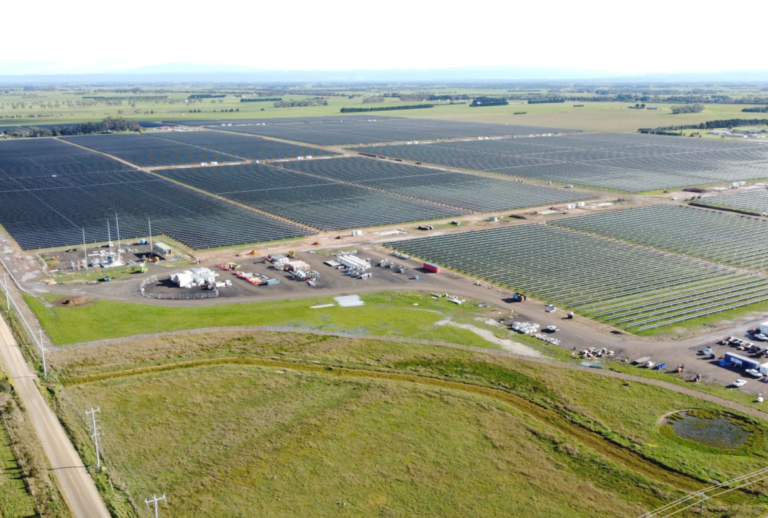
Australia’s utility-scale solar and wind assets generated a combined 5.44TWh across the National Electricity Market (NEM) in September 2026, up 7% from 5.1TWh in September 2025, according to Rystad Energy senior analyst David Dixon.
Utility-scale solar drove much of the state-level growth. New South Wales, Queensland and Victoria each recorded their highest monthly utility PV generation on record for September, at 841GWh, 645GWh and 267GWh, respectively, Dixon wrote in a detailed LinkedIn post last week.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
Victoria led all states on combined output, generating 1.52TWh across both technologies, comprising 1.25TWh from wind and 267GWh from utility PV.
The top-performing utility PV assets for the month were concentrated in New South Wales and Queensland, each recording a 35% AC capacity factor.
This includes ACEN Australia’s Stubbo stages 1 and 2 in NSW, Hana Financial Investment’s Columboola in Queensland, and the ENEOS Group and Sojitz Corporation joint venture at Edenvale, also in Queensland.
Wind performance was led by Potentia Energy’s Flat Rocks in Western Australia at 55%, followed by two Tasmanian assets, Atmos Renewables’ Cattle Hill at 49% and the Atmos Renewables and Palisade Investment Partners joint venture at Granville Harbour at 48%.
Wind generation moved in the opposite direction to solar nationally, falling or holding flat in every NEM state except Queensland. Total wind output was down by approximately 86GWh compared with September 2025.
Curtailment continues to ease as battery storage capacity expands
Utility PV curtailment fell to 22% of available generation in September 2026, down from 26% in September 2025, while wind curtailment held broadly flat at around 13%.
The improvement extends a trend already visible in Rystad’s August data, when NEM utility PV curtailment fell to around 9% of available generation, down from roughly 18% a year earlier, as utility-scale solar generation climbed to a combined 4.99TWh with wind.
September’s curtailment rate remains structurally higher than August’s, reflecting the seasonal pattern in which curtailment tends to peak in spring as solar output rises faster than underlying demand, but the year-on-year direction in both months points in the same direction.
Spot prices stayed low across the NEM during September, with every state averaging below AU$65/MWh (US$43/MWh) and the three southern states, South Australia, Tasmania and Victoria, all below AU$40/MWh.
The Wholesale Electricity Market (WEM) in Western Australia moved in the opposite direction, averaging around AU$110/MWh, the highest recorded for the month of September since the market began.
Gas-fired generation across the NEM totalled just 455GWh for the month, the first time September gas output has fallen below 500GWh.
Investment activity continued alongside the generation data. Several utility-scale projects reached financial close during September, including Atmos Renewables’ 470MW Parron wind farm and Foresight Group’s 130MW wind farm, both in Western Australia, as well as Birdwood’s 400MW/1,860MWh battery storage project.
Atmos Renewables also reached financial close on the 400MW/1,600MWh Teebar Battery in Queensland as the month closed out.
That pace of deployment builds on a broader run of record-setting data across Australia’s clean energy sector through 2026.
AEMO’s FY26 annual report recorded 9.1GW of new generation and storage capacity reaching full output in the NEM over the year, more than double the volume achieved in FY25, with the broader connections pipeline growing 42% to 75.4GW.
The Clean Energy Regulator separately reported its strongest quarter yet for rooftop solar installations, household battery uptake and large-scale solar investment, with 1.8GW of generation capacity reaching final investment decision, the strongest quarterly result since the regulator began tracking investment activity.