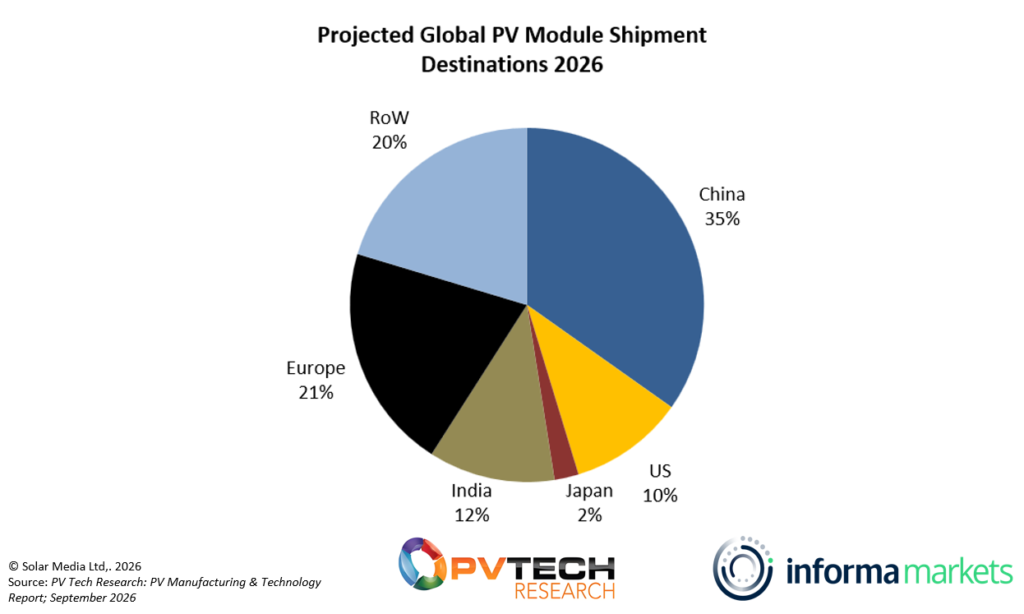
Welcome to the PV Chart of the Week, produced in tandem with our colleagues at PV Tech Research. This week, we look at the projected global PV module shipments for 2026.
Once again, China will remain the main destination for the supply of modules this year, however its share of the pie is set to decrease by 12 percentage points from 47% in 2025 to 35% in 2026.
Try Premium for just $1
- Full premium access for the first month at only $1
- Converts to an annual rate after 30 days unless cancelled
- Cancel anytime during the trial period
Premium Benefits
- Expert industry analysis and interviews
- Digital access to PV Tech Power journal
- Exclusive event discounts
Or get the full Premium subscription right away
Or continue reading this article for free
This would correlate with the drop in installed solar PV capacity in the past 12 months, since the country launched a new pricing reform for grid-connected renewables that took effect in June 2025. In the first four months of 2026, solar PV installations dropped by 51%, with only 50.9GW of new capacity added compared to the nearly 105GW registered in the same period of 2025.
Moreover, a forecast from the Chinese trade body, the China Photovoltaic Industry Association (CPIA), earlier this year estimated a decrease in solar PV installations for 2026 in China, from a record 315GW registered in 2025 to between 180GW and 240GW this year. And the country has also been facing curtailment issues for both solar PV and wind projects.
Outside China, Europe will be the second-largest market for PV module shipments in 2026, with PV Tech Research forecasting a 21% share. This represents a five percentage point increase from 2025. In 2026, Europe is set to slightly outperform the rest of the world, which is forecast to have a 20% share of the global PV module shipment, up from the 17% reported last year.
Finally, India is also set to increase its share in 2026 with a four percentage point increase from 8% in 2025 to 12% in 2026, while both the US and Japan will remain at 10% and 2%, respectively.